
- Why Items Become Non‑Returnable
- How Paid Return Coverage Works
- Credit‑Card Return Protection
- Shipping Protection vs Return Coverage
- How Return Coverage on Non‑Returnable Items Works in Practice
- When It’s Worth Paying for Return Coverage on Non‑Returnable Items
- What to Check Before You Rely on Return Coverage
Last Updated on September 18, 2026 by Ewen Finser
Though it might seem like a contradiction, it is sometimes possible to return non-returnable items. There are a few ways to do this, but the most reliable is buying return coverage on non-returnable items. You’ll typically see this type of coverage as an optional add-on at the checkout of an online store.
So, how does it work?
Why Items Become Non‑Returnable
Ecommerce stores label certain products as “final sale” or “non‑returnable” to protect margins or deal with items that are hard to resell.
This is common for items such as:
- Clearance or sale items. Deep discounts often come with a “sold as‑is” policy.
- Customized or personalized products. Monogrammed, tailored, or made‑to‑order goods usually can’t be returned because they can’t be easily resold.
- Hygiene‑sensitive categories. For hygienic reasons, swimwear and underwear are generally non-returnable.
- Perishables and time‑sensitive goods. Food, flowers, and event‑related products typically aren’t returnable once delivered.
It’s worth noting that return coverage options won’t cover all these categories of goods. You might get protection for a jacket that’s 70% off in a summer sale; you probably won’t have that option for a DoorDash order.
How Paid Return Coverage Works
The availability of this type of coverage depends on individual stores. If a retailer wants to provide its customers with this option, they’ll partner with a third-party coverage provider (like Seel or Redo).
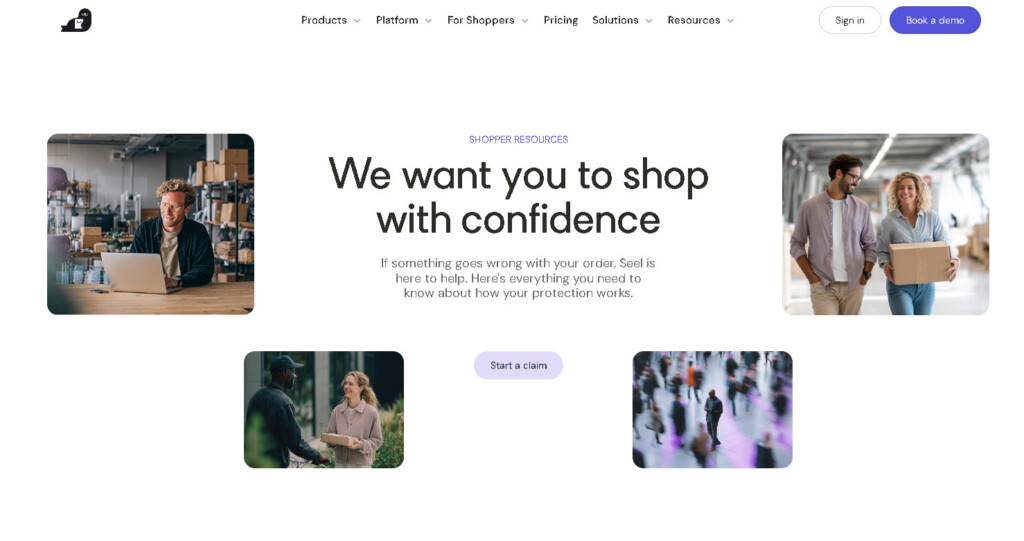
You pay a small extra fee to this coverage provider on top of your order to add protection to specific items (often selected line‑by‑line, so that you can pay for protection on some items and not others).
Then, if you change your mind during the coverage window, you file a return (generally through the provider’s portal rather than the store’s normal returns page), and the provider funds the refund if everything checks out.
Refunds are typically paid by the protection provider, not through the store’s normal refund workflow. The protection fee itself, original shipping charges, and sometimes a flat return‑shipping fee may be excluded from the refund, depending on the coverage provider’s policies.
Credit‑Card Return Protection
Aside from specialist third-party coverage, you may be able to access return protection through your credit card.
Credit cards offer a different kind of return coverage, which kicks in after the store refuses a return. You may automatically have a right of return in relation to a product if you used your credit card to buy that product (depending on the terms and conditions of your card provider). There’s no widget at checkout; if you pay with a card that includes return protection, coverage is automatic for eligible purchases.
Many cards give you 60–90 days from the purchase date to file, beyond the store’s return window.
However, there are still proof requirements, and you must generally be able to show:
- The original receipt.
- A card statement showing the full purchase charged to the eligible card.
- Evidence that you tried and were refused a return by the retailer (emails, chat transcripts, or written confirmation).
Issuers will also require items to be in like‑new condition, often in original packaging, and may ask you to ship the item to them for evaluation. Plus, refunds are capped (commonly at $250–$300 per item and around $1,000 per year per card account, depending on the issuer).
So, credit‑card return protection can come in handy when a retailer simply refuses a return, but it requires more paperwork and has lower per‑item limits than many dedicated checkout return‑coverage products.
Shipping Protection vs Return Coverage
It’s easy to confuse shipping protection with return coverage, because the third-party providers often offer both (usually inside the same checkout widget). However, these are two completely different forms of protection, so it’s crucial that you understand the difference between them.
Shipping protection covers your order during transit. It deals with loss, theft, and damage between the warehouse and your door. Return coverage, on the other hand, gives you the right to send an item back after it arrives when you wouldn’t otherwise have that right, even if it’s in perfect condition.
For example, Seel offers a Worry-Free Purchase product that provides return coverage, while its Worry-Free Delivery option gives you shipping protection.
When you’re deciding whether to add a protection line at checkout, check if the language talks about delivery issues only, or explicitly mentions returns on clearance/final sale items—that tells you whether you’re buying shipping protection or true return coverage.
How Return Coverage on Non‑Returnable Items Works in Practice
I’m going to use Seel’s Worry-Free Purchase as the example here, as it’s the return coverage widget you’re going to see most often at checkouts (and the one that generally provides the most robust coverage for non-returnable items):
- At checkout: You see a widget offering Worry‑Free Purchase on eligible items, sometimes including those marked final sale or clearance. You choose which items to cover and pay a small fee that appears as a separate line in your order summary.
- After delivery: Your coverage email and Seel’s shopper resources page confirm which items are covered and show that you have 7 days from delivery to change your mind.
- If you decide you don’t want the item: Within those 7 days, you go to Seel’s Resolution Center, enter your order details, and select the items to return. You may need to confirm that the items are in acceptable condition and follow instructions to ship them back within another short window.
- Refund: Once Seel receives and approves the return, it funds the refund for the item’s purchase price via the payout method it supports. The store keeps the sale revenue; Seel’s protection fee and any specified return‑shipping charge are not refunded.
When It’s Worth Paying for Return Coverage on Non‑Returnable Items
Return coverage really only makes sense in a limited set of circumstances, such as:
- High‑value or high‑risk final sale: Luxury fashion, hype sneakers, niche electronics, or custom items where a bad fit or mismatch would be costly.
- Unfamiliar brands or fit‑sensitive categories: New apparel labels, technical gear, or safety equipment where sizing and comfort are hard to predict.
- Strict store policies: Retailers with short windows or store‑credit‑only returns where a separate coverage product gives you a safety net.
If the item is cheap or the store already offers generous returns, card‑based return protection or the store’s native policy may be enough. But when you’re on the fence about a final sale purchase, dedicated return coverage may be a smart investment.
What to Check Before You Rely on Return Coverage
Before you assume a non‑returnable item is covered, double‑check:
- Is the protection really about returns? Look for wording like “7‑day return protection,” “return coverage,” or “Worry‑Free Purchase,” not just “shipping protection” or “order protection.”
- Does it explicitly mention non‑returnable items? Some third-party return coverage platforms exclude final sale items, so you need to read the fine print.
- Which items in your cart are covered? Coverage applies only to items you actually added it to at checkout; they’re usually flagged in confirmation emails or your account.
- What’s the timeline and process? Checkout coverage tends to have short windows (like 7 days from delivery), while credit‑card protection works for 60–90 days after purchase but requires proof that the retailer refused the return.
- What are the limits and exclusions? Both card benefits and coverage products exclude certain categories (vehicles, medical equipment, high‑value jewelry, some perishable goods) and cap refunds per item and per year. Again, always read the fine print.
If you use it sensibly, return coverage can be a great way to add peace of mind when you’re making potentially risky purchases.